The 2026 Blue Wave Midterm Election Results and Possible Impacts
The dust has begun to settle, and the political picture is becoming clearer for what the next two years will have in store, or at least as clear as it can be. The words attributed to Tuesday’s result are “historic” and “generational”. A Democrat won a senate race in Texas for the first time since 1988. The Governor’s race was won by a Democrat for the first time since 1990. Kansas elected a Democrat for the first time since 1932. The first Muslim-American U.S. Senator was elected in Michigan. In more recent history, it has been over twenty years since Georgia had a Democrat Governor and two Democrat senators at the same time. The last Democrat Senator from South Carolina was Fritz Hollings (elected in 1998) before Annie Andrews won her race. No doubt even more historic facts about the election will come to light in the coming days and weeks.
Midterm elections are always difficult for the incumbent President. The raucous enthusiasm of victory in a nationwide election gives way to the reality of governing a country of almost 350 million people subdivided into 435 Congressional districts and 100 Senate seats. Frustration with the party in power happens almost like clockwork. Add into that an unpopular war with Iran and tariff policy impacting constituents’ bank accounts at the grocery store and gas station, and it was a recipe for trouble for the Republicans in 2026.
Since Ronald Reagan’s first midterm election in 1982, the average losses by the President’s party is about twenty-two House seats and three Senate seats (the actual numbers are -22.08 and -3.25 but you can’t have a fractional congress member, so I had to round). There is no set definition on what constitutes a wave election, but the idea is that the party out of power rides that wave of dissatisfaction against the President’s party and regains control of one or both chambers of the legislature. For my purposes, a wave election is an above-average loss for the party holding the presidency. I consider a House wave to be anything over twenty-five lost seats and a Senate wave to be anything over five lost seats.
With that in mind, the number of wave elections in the House and Senate is both six. 1982, 1994, 2006, 2010, 2018 and 2026 saw a wave election for the House. In 1986, 1994, 2006, 2010, 2014 and 2026 the Senate got hit by a wave. It’s possible to have a wave in the House and not the Senate and vise versa. There were four instances where both chambers were hit with a wave at the same time: 1994, 2006, 2010 and now 2026.
Focusing on those three instances where both the House and Senate flipped (unfortunately, I don’t have the data for 2027-2028 just yet), the S&P 500 had the following returns until the end of the next election year:
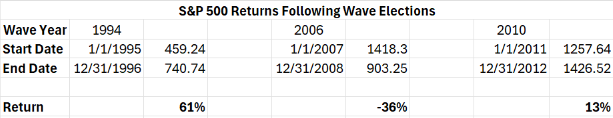
Mileage varies from wave to wave. 1994-1996 saw excellent returns following the Newt Gingrich “Republican Revolution” wave. The returns for 2006-2008 will be remembered through the lens of the events of the Great Financial Crisis. From 2010 through to the end of 2012, the market rose slow and steady between the two previous extremes. It remains to be seen what we can expect from this wave election in the markets.
Economic/Market Impact: The S&P 500 closed the day after the electionup 1.58%. (NOTE: I would not extrapolate that type of daily return from now until December 31, 2028. As of this writing here on November 5, 2026, the prior day’s gains have been given back and then some). Given the new state of play in Washington DC, there will be plenty of reverberations to come in the markets and the economy
Certain sectors could be more impacted by an agenda of increased governmental regulation. There could be more funding and tax breaks for green energy companies and restrictions on fossil fuel energy and AI buildouts. AI is here to stay, but there could be a slowing of the infrastructure buildout. Many Republican and Democrat candidates were unified in their opposition to data centers being built in their districts. It is a hot-button issue, but it seems likely that it’s a matter of where and not a matter of if they should be built. Technology could see an unwinding in the short term if there are plans for increased regulatory control over AI and the construction of data centers.
If the war in Iran were to wind down, that would be a negative for defense if Congress does not want to keep footing the bill. However, if the conflict in Ukraine is to be sustained, then it would likely be American arms that helps continue the fight. $73B, or roughly 35% of military aid has been provided by the United States. That number could increase under the new Congress.
In the Healthcare sector, several Democrats, most prominently Senator-elect El Sayed ran on Medicare For All. While that seems unlikely to pass, it is possible now for Congress to either bolster Obamacare or give more funding to hospitals that had been cut by the Big Beautiful Bill, especially those in rural areas.
Fiscal Policy: With the flip in both the House and Senate, forget about the $5,000 check Americans were told they’d receive if Congress stayed Republican. Always a longshot, it is probably safe to say that the final stimulus check of the Trump era is cancelled. Congress will instead be focusing on policies that could naturally lower costs of living, such as attempting to reduce tariffs as well as settle the conflict in Iran. The overall goal being the mitigation of the K-shaped economy that has pervaded since earlier this decade.
Domestic Policy: Simply put, expect less to get done at the federal level now that there is a split between the legislative and executive branches. On election night, Trump drifted between being conciliatory in defeat, saying he accepts the results of the election. He even hinted at a willingness to deal with Democrats. But prior to that, he’d posted a photo on social media with his signature red hat but with the usual moniker of “Make America Great Again” replaced with a singular, large-font VETO, indicating he may be less than willing to make a deal with the Democrats.
Immigration: It is unlikely there will be sweeping changes to immigration policy. Previous budgets included funding for ICE through 2029, probably knowing that a wave election could derail the department’s funding. It would be difficult to defund/diminish the budget since it’s already been earmarked. Republican members will want to maintain immigration enforcement, so it seems unlikely that a change will happen. Despite gaining at least seven seats in the Senate, it is unlikely the Democrats will be able to add six defections by Republicans. Additionally, the courts have broadly approved Trump’s policies. The main economic impacts for the administration on their immigration policy will be a continuing restriction on labor force growth as a result of continuing restrictions on immigration.
Trade and Tariffs: There is a distinct possibility that tariffs are rolled back in some form or fashion. The tax on imports is not a natural Republican issue as they consider themselves the party of free enterprise. They don’t want blocks to the movement of goods or services. Trump likes them, but even members of his own party don’t. Reducing the tariffs is an easy win for Democrats who ran on decreasing the cost of living while allowing Republicans to gain some credit for bipartisanship. Over the first 2 years of Trump’s second term, Congress ceded authority on tariffs under “emergency tariffs” imposed unilaterally by the President. Now with a Democrat majority, it is likely that Congress will attempt to take the power of the purse back. Lower tariffs will lower costs of living. As one analyst stated, “I don’t know how fast it will happen, but the tariff high water mark is behind us.”
In terms of trade, the President’s combative attitude towards Canada and Mexico, our two largest trading partners, could be softening as he is reined in by a Congress looking to ease the President’s inflationary tactics. Smoother relations with our neighbors to the north and south could ease some of the tensions surrounding tariffs. A decrease or elimination of them would lead to a natural disinflation.
Geopolitics: Earlier this week, there was speculation that the President would escalate the war with Iran. However, following Tuesday’s results, he stated early Wednesday morning that would not escalate. Iran would probably like a deal as well. They currently have leverage as high gas prices and inflation on the increased cost of the movement through the Strait of Hormuz may have cost Trump the election. There will also be pressure on the new Congress to wind down the war with Iran while reining in their nuclear ambitions. Additionally, President Trump stated on Tuesday morning that he plans to halt an annual $4B payment in aid for Israel.
Ukraine may go the other way, with Democrats and many Republicans willing to help fund their war against Russia. Trump has been somewhat of a reluctant ally to Ukrainian leadership and was seen as being closer with Russia that made some in his own party uncomfortable. Ukraine should see more support from both sides of the American political aisle now. The war for the defense of Ukraine is seen as a key builder to repair ties with traditional overseas allies. It is possible that even if Trump vetoes aid to Ukraine, there could be an override if Congress can muster a 2/3 vote, which could put the U.S. in better standing with Europe.
While the full effects of the election won’t be known until we live through them, the next two years will likely see a fair amount of gridlock on contentious issues such as immigration and ongoing overseas conflicts. We could see a decrease (but by no means an elimination) of the focus on AI with a shift toward green energy. We may see a thawing of previously cold foreign relations and as a result, a softening of tariffs by both the U.S. and their counterparties. For those invested in equities, especially if their portfolio is weighted more towards US-based companies, they should continue to remain broadly diversified across sector and capitalization as we make our way through these current generational and historic times.

Gavin Anderson, CIMA®
Performance Analyst